A "bruised" credit score — something in the 600 to 650 range — doesn't shut the door on getting a mortgage. But it does change the math, sometimes by tens of thousands of dollars over the life of the loan, and most people never see the actual number, just a vague sense that their rate will be "a bit higher."
What actually changes at a lower score
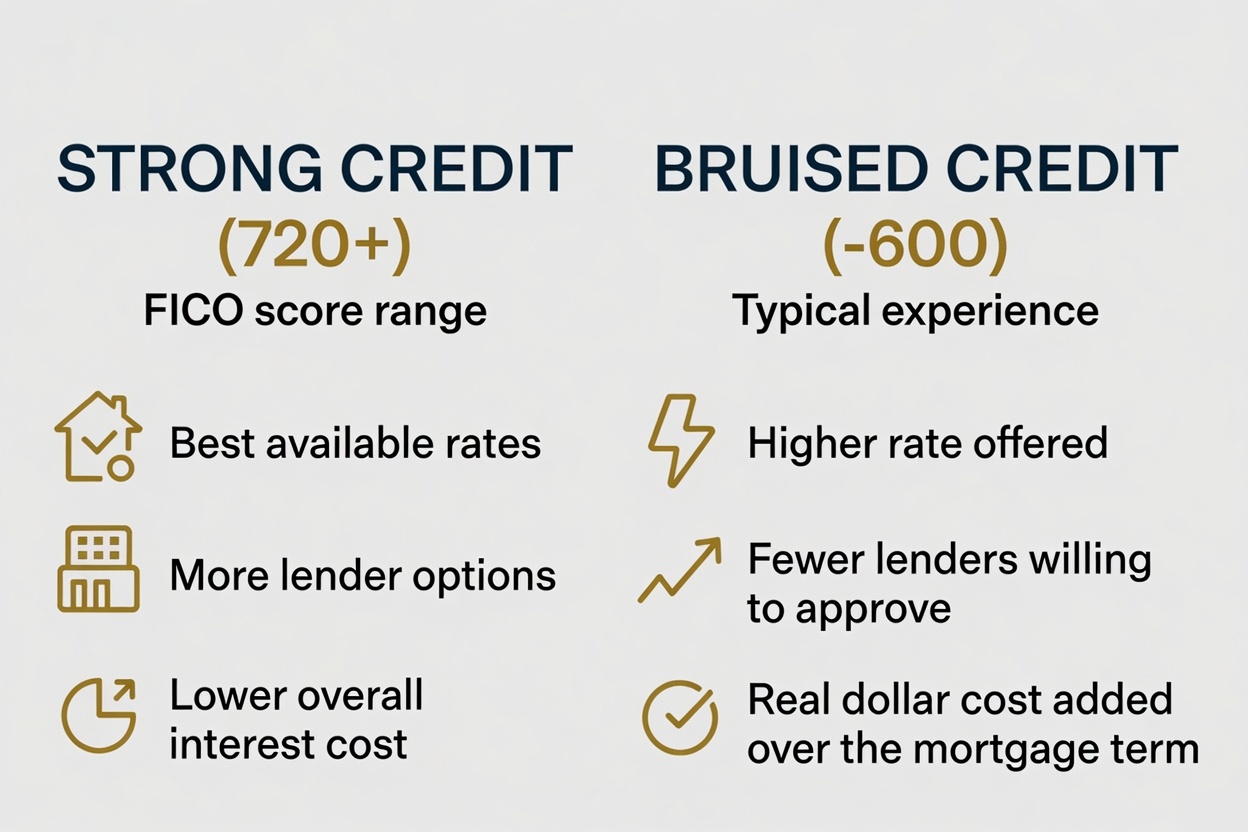
Lenders price risk. A lower credit score signals more risk, and that shows up as a higher rate offered, and fewer lenders willing to approve the file at all. Some traditional lenders simply won't go below certain thresholds, which narrows your options before you even get to the rate conversation.
The gap between a strong score and a bruised one isn't a rounding error. Applied across a 25-year amortization, it's real money — often tens of thousands of dollars in additional interest.
Why the CMHC part gets misunderstood
A common assumption is that a score below 680 or so disqualifies you from CMHC-insured financing entirely. That's not accurate — CMHC has approved insured mortgages well below that threshold, including scores in the 600s, depending on the rest of the file. The real constraint usually isn't a hard credit cutoff — it's the combination of score, income stability, and debt load that a lender is weighing together.
What you can actually do about it
- Know your real number before you shop. A pre-approval conversation should include an honest look at your credit, not just an assumed range.
- Understand which lenders actually work with your score. Not every lender has the same appetite — a broker who knows the lender landscape can steer you toward the ones that fit, rather than the ones that reject you outright.
- Consider whether a short delay is worth it. Sometimes a few months of deliberate credit repair meaningfully changes the rate you're offered — worth knowing before you commit to today's number.
Bottom line
A bruised score is a real factor, not a life sentence. The mistake is assuming the worst without actually finding out where you stand and what it changes — that's a conversation worth having before you start house hunting, not after an offer falls through.
Your credit score is a number, not a verdict. Call 902-465-5533 — I answer.
Patrick Sawler
Principal Broker, Craigburn Capital
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s— You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.
p.s.s— I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario (M23006699).
p.s.s.s— You can download my new mortgage app here
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Ready to have a real conversation? Call 902-465-5533 or start your application here.