Both a second mortgage and a refinance let you tap into the equity you've built in your home. Past that, they're not the same tool at all — they work differently, cost differently, and fit different situations. Mixing them up can mean paying more than you need to, or breaking something you didn't need to touch.
What actually happens with each one
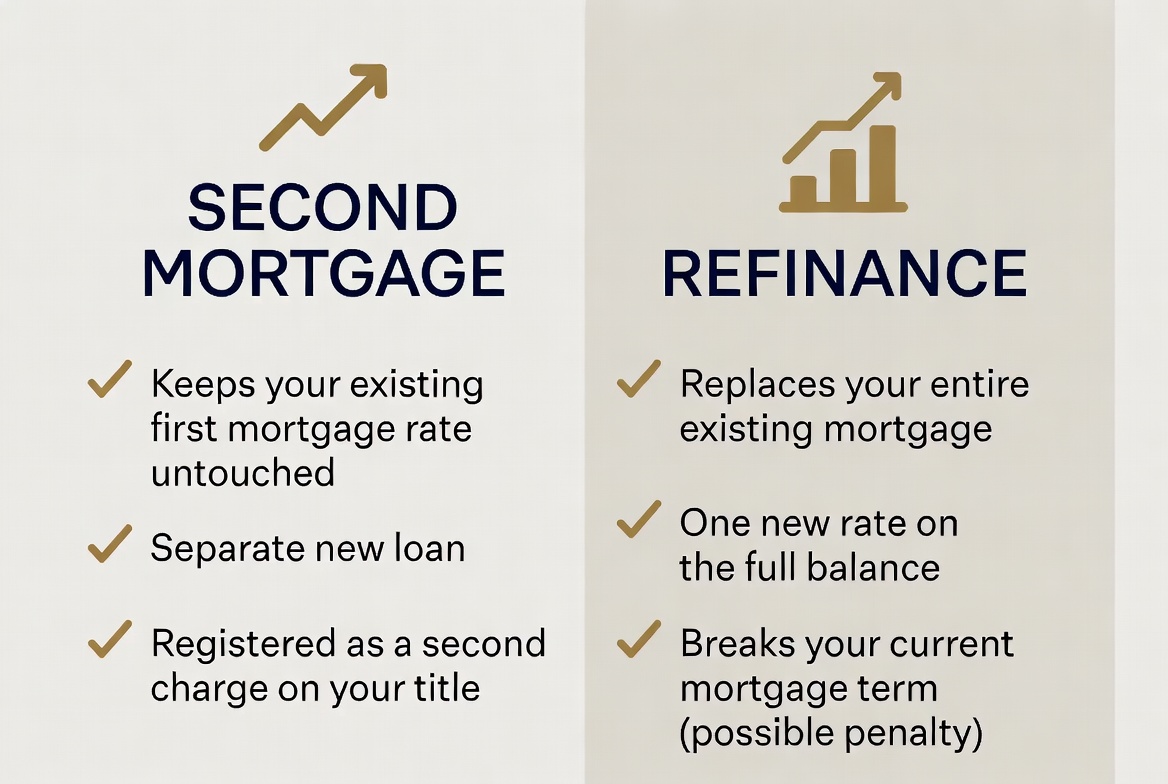
A second mortgage is exactly what it sounds like: a separate loan, registered as a second charge behind your existing first mortgage. Your original mortgage — rate, term, everything — stays completely untouched. The second mortgage sits on top of it, usually at a different (often higher) rate, and gets paid down independently.
A refinance replaces your entire existing mortgage with a new one. There's no "on top of" — the old mortgage is gone, and you have one new loan, one new rate, on the full balance including whatever additional funds you're pulling out.
A second mortgage adds a second loan. A refinance replaces the loan you already have. That single distinction changes almost everything else about the decision.
Why the difference actually matters
If your current mortgage has a great rate locked in, refinancing means giving that rate up entirely — even on the portion of the balance that has nothing to do with why you're borrowing more. A second mortgage leaves that original rate alone and isolates the new borrowing on its own terms.
On the other hand, refinancing consolidates everything into one payment, one rate, one lender relationship. A second mortgage means two payments, two lenders, and two sets of terms to track — simpler in some ways, more complex in others.
When does each one make sense?
A second mortgage tends to make sense when your existing rate is meaningfully better than what's currently available, or when your first mortgage has a penalty for breaking it early that would outweigh the benefit of combining everything into one loan.
A refinance tends to make sense when today's rates are actually better than what you're currently locked into, when you want the simplicity of a single payment, or when the amount you need to borrow is large enough that carrying two separate loans starts to feel unwieldy.
The number that actually decides it
There's no universal right answer — it comes down to your specific rate, your specific penalty (if any), and how much you're looking to borrow. That's a real calculation, not a guess, and it's worth running before you assume either option is automatically the cheaper one.
Not sure which one fits your situation? Let's figure it out. Call 902-465-5533 — I answer.
Patrick Sawler
Principal Broker, Craigburn Capital
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s— You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.
p.s.s— I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario (M23006699).
p.s.s.s— You can download my new mortgage app here
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Ready to have a real conversation? Call 902-465-5533 or start your application here.